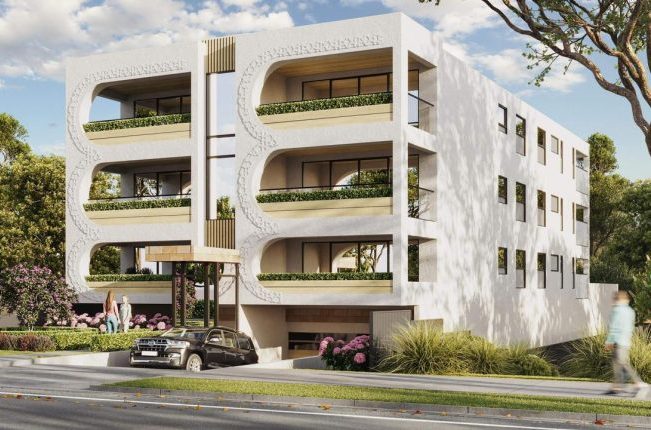
A change to the law that exempts low-rise buildings from Home Owners Warranty Insurance could bring an unexpected benefit to owners in new apartment blocks, but will certainly be a mixed blessing.
From December 1, the Home Building Amendment (Insurance Cover) Regulation 2026 will introduce an exemption from the Home Building Act 1989’s insurance requirements for residential building work involving the construction of a Class 2 building containing more than two sole-occupancy residential units, writes strata lawyers Bannermans.
Developers selling land on which that work has been, or is to be, carried out will also be exempt from the corresponding section 96A insurance requirements.
Clearly recognising the push to have more low-rise apartment blocks in areas where they have previously been locked out, the government will pull new low-rise blocks out of mandatory insurance cover and into line with the defects bond system for larger schemes.
However, it will have a significant effect of developers’ ability to influence decision making about defect claims. As it stands, developers in apartment blocks covered by HOWI, can still vote on defects issues. That includes schemes of three storeys or less.
The relevant, somewhat roundabout part of NSW strata law says in section 15 of schedule 1 that “the developer or lessor of a leasehold strata scheme is not entitled to vote, or exercise a proxy vote, on a matter concerning building defects in, or the rectification of building defects in, building work to which Part 11 of this Act applies.”
Part 11 of the Act says in section 191 that “this Part does not apply to building work if the work is subject to the requirement to obtain insurance under Part 6 of the Home Building Act 1989.” Buildings of three storeys or less currently require insurance.
Back in the day, this was intended to cover small developments of only a few apartments but there has been an increase in low blocks with multiple units that are exempt from the law that forbids developers from taking part in defects discussions.
We know of one in the Illawarra which is less than three storeys high, with about 80 units, where the developer routinely participates in discussions about defects and then sits on the committee to do the same, claiming there is no conflict of interest.
The chair and treasurer of that block say a conflict of interest only occurs when money changes hands, which is either incredibly naïve or massively complicit, a typical view in a schemes where owners are anxious not to cause a fuss.
Anyway, the option for developers to influence owners corporation general meetings decisions on defects will disappear for new blocks of more than two units built after December 1.
So, is keeping developers out of defects decisions a worthwhile trade-off for shifting insurance cover to the building bond scheme? It very much depends on how informed and energised the apartment owners are.
You can read the Bannermans’ fact sheet on the law changes HERE.
› Forums › Current Page
Change to Home Owners Warranty Insurance will shift low-rise blocks into the bond scheme but remove the right for developers to vote on defects decisions.
[See the full original blog post at: Building insurance change a mixed blessing To comment on the post, click on reply here.]
If you want to be alerted when anyone replies to your posts or responds to this topic, please register and login, then you will be able to subscribe to the topic. The opinions offered in these Forum posts and replies are not intended to be taken as legal advice. Readers with serious issues should consult experienced strata lawyers. NB: Longer threads may spill over to additional pages - look for the numbers on the bottom right, under the last post.
› Forums › Current Page
› Forums › Current Page